Why Schedule a Retirement Planning Strategy Session Now
Most people within ten years of retirement have never sat down and mapped out how the pieces fit together. A retirement planning session is a structured meeting with a financial professional to review your accounts, goals, taxes, and income sources, then build one written plan you can act on.
Here’s why timing matters. Once you stop earning a paycheck, you lose the easiest tool you had for fixing problems: new income. A market drop two years before retirement hits harder than the same drop at 45, because there is no time to earn the money back.
Below, we’ll walk through how to prepare, what to bring, what to ask, and what happens after the meeting. The goal is simple: you walk in organized and walk out with a plan.
Watch Out The most common mistake is treating a strategy session like a sales pitch instead of a working meeting. Show up without your statements or your goals, and you’ll get generic advice that fits no one. Bring your documents and the meeting pays for itself.
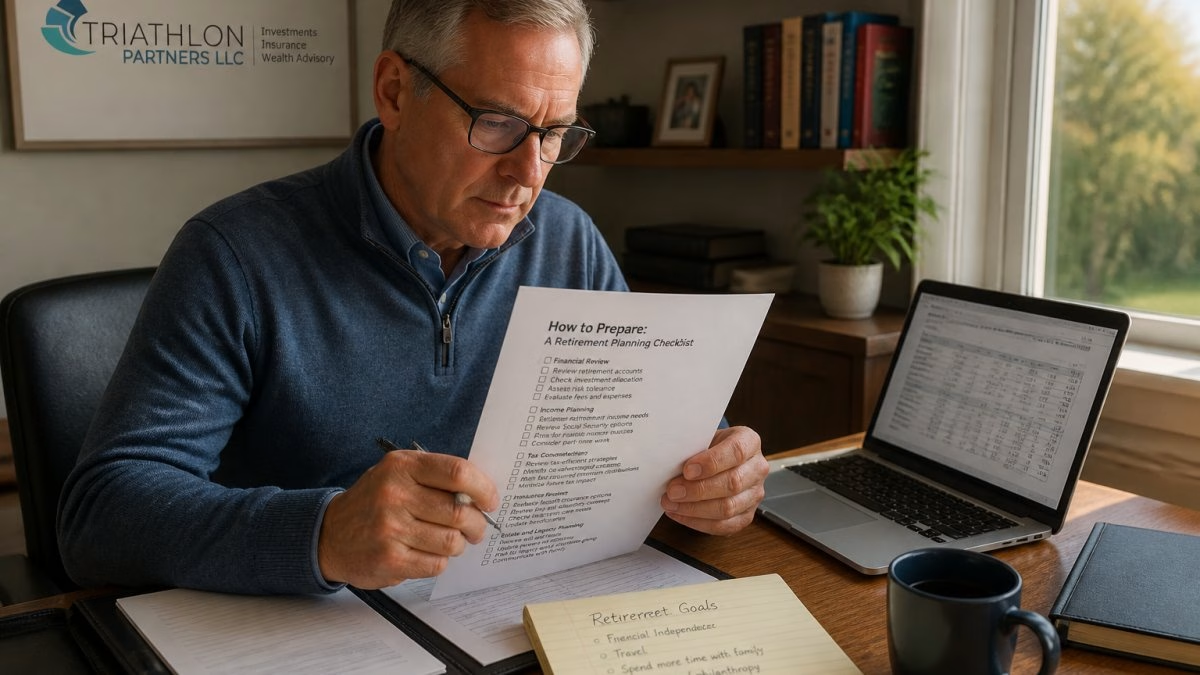
How to Prepare: A Retirement Planning Checklist
Preparation is what separates a useful session from a wasted afternoon. The best-prepared clients leave with a plan they can execute within a week. Everyone else leaves with homework.
A common approach is to gather three things before you call: your documents, your goals, and your questions. We’ll cover each below.
A professional in their late 50s sitting at a tidy home desk, reviewing a printed checklist alongside a laptop showing account statements and a notepad with handwritten retirement goals, warm afternoon light
Documents and Account Statements to Gather
Pull together your most recent statements from every account. This includes 401(k)s, IRAs, brokerage accounts, bank accounts, and any pensions. If you own a business, add your last two years of tax returns and a current balance sheet.
Also gather:
Social Security statements from your online account
Recent tax returns, at least two years
Insurance policies, including life, disability, and long-term care
A list of any debts and their interest rates
Estate documents, such as wills and trusts
Don’t worry about perfect organization. A folder and a simple list will do.
Clarifying Your Retirement Goals and Timeline
Numbers alone don’t make a plan. Your goals do. Write down when you want to stop working, or reduce your hours. Then describe the life you want: travel, a second home, helping family, or simply less stress.
Be honest about trade-offs. A retirement date two years earlier usually means spending less or saving more now. A retirement planning session works best when you bring real preferences, not just a wish list.
Questions to Ask a Retirement Planner
The right questions protect your money and your time. Ask about fees, how the advisor gets paid, and whether they act in your best interest. Ask how they handle taxes, insurance, and income together, not just investments.
Then ask the harder ones. What happens if the market drops 30% right before I retire? How will you adjust my plan? What am I missing that my current advisor hasn’t mentioned?
Fees, Fiduciary Status, and Conflicts of Interest
A fiduciary is a professional who is legally required to put your interests first. Ask directly: “Are you a fiduciary at all times, or only when giving certain advice?” The answer matters, because some advisors earn commissions on products they recommend.
Ask how fees are structured. Some charge a percentage of assets, some charge a flat fee, and some earn commissions. The SEC investor guidance on working with financial professionals explains how to check an advisor’s registration and disciplinary history.
Pro Tip Ask for the fee in dollars, not percentages. “One percent” sounds small until you see it’s $10,000 a year on a $1 million portfolio. A good advisor will answer that question without hesitation.
How Long Is a Typical Retirement Strategy Session?
A typical first retirement planning strategy session runs 60 to 90 minutes. That is enough time to gather facts, confirm goals, and agree on next steps, but not enough to deliver a finished plan.
Here is a realistic timeline you can plan around:
Introductory call (15-30 minutes, often free). A short fit check. The advisor asks about your assets, income sources, and timeline, and you decide whether to book a full session.
Discovery session (60-90 minutes). The working meeting. You bring documents, the advisor takes notes, and you leave with a list of open items.
Plan presentation (60-90 minutes). The advisor walks through recommendations, trade-offs, and a draft action plan.
Follow-up review (30-60 minutes, often within 90 days). You confirm what was implemented and adjust for anything that changed.
Complex situations, a business sale, a pension decision, a spouse with a health concern, or a large concentrated stock position, commonly stretch to three or four sessions.
A Practical 90-Minute Agenda
If you want the meeting to be productive, ask the advisor to share an agenda in advance. A common structure looks like this:
Minutes 0-10: Confirm the goal. Is this an introductory meeting, a second opinion, or the start of an ongoing relationship? The answer changes what the advisor should cover.
Minutes 10-30: Review the facts. Accounts, income sources, debts, insurance, tax situation, and any pension or Social Security estimates.
Minutes 30-55: Discuss goals and trade-offs. Retirement date, spending level, healthcare coverage before Medicare, and what you are willing to give up to retire earlier.
Minutes 55-75: Identify gaps and conflicts. Tax sequencing, Roth conversion windows, required minimum distributions, and any mismatch between your risk tolerance and your portfolio.
Minutes 75-90: Agree on next steps. Who does what, by when, and when you will meet again.
If the advisor cannot describe an agenda, that is useful information about how organized the relationship will be.
What to Expect After the Session
The follow-up is where most plans stall. Before you leave, confirm four things in writing:
A summary of what was discussed and what the advisor recommends
A task list with owners and target dates
The date of the next review
A direct contact for questions between meetings
A written plan that never gets reviewed is just a document. Most practitioners recommend a formal review at least once a year, and an off-cycle check after any major event: a job change, a health diagnosis, a market drawdown, or the death of a spouse.
Pro Tip Ask the advisor to send a one-page summary within five business days. If that summary does not arrive, the plan probably will not either.
What a Session Can and Cannot Do
A strategy session can give you a clear picture of where you stand, surface tax and insurance gaps you did not know existed, and produce a realistic retirement date based on your actual numbers. It cannot guarantee investment returns, replace your attorney or accountant for legal and tax filings, or fix a plan that has no follow-through. Be wary of anyone who promises a specific outcome, good planning is about managing risk and trade-offs, not certainty.
Retirement Planning Checklist for Business Owners
Business owners face a problem employees do not: their wealth is tied up in one asset. A retirement planning strategy session for an owner has to cover both the company and the personal balance sheet, because the two are linked, and the meeting itself should be structured differently than a standard session.
What to Bring to the Session
In addition to the standard documents (recent statements, tax returns, insurance policies, estate documents), owners should bring:
A current valuation or a reasonable estimate of the business
Your exit timeline and who might buy the business, a partner, a key employee, a competitor, or an outside buyer
Buy-sell agreements and any key employee documents
Retirement plans offered to employees, such as a 401(k), SEP, or profit-sharing plan
Personal accounts held separately from the business
Any outstanding business debt and its terms
How to Structure the Meeting
A standard 90-minute session is usually not enough for an owner. Ask for a two-part meeting:
Part one: the business. Valuation range, exit options, tax treatment of a sale, and how the proceeds would flow to you personally.
Part two: the personal plan. How the after-tax proceeds fit into your retirement income, what you will live on before a sale closes, and how your personal portfolio should be positioned in the meantime.
The goal is to convert business equity into personal wealth without losing a large share to taxes. That takes coordination between your tax advisor, your attorney, and your financial planner, and the session is the place to map out who does what.
Questions Specific to Owners
If I sell in three years versus five, how does that change my retirement date?
What is my after-tax number under each exit scenario?
How do I fund my lifestyle if the sale takes longer than expected?
What happens to my retirement plan if I keep the business and hire a manager?
Key Takeaway For business owners, the exit date and the retirement date are the same decision. Pick one without the other and the plan will not hold together.
What a Strategy Session Can and Cannot Accomplish
A strategy session can give you a clear picture of where you stand and a written plan for the next steps.
It cannot guarantee investment returns or predict markets. It cannot replace your attorney or accountant for legal and tax filings.
Be wary of anyone who promises a specific outcome. Good planning is about managing risk and trade-offs, not certainty.
Building Your Action Plan: Follow-Up After the Session
The follow-up is where most plans die. You leave motivated, then life gets busy, and the folder sits on the shelf.
After your session, expect:
A written summary of recommendations
A list of tasks with deadlines
A scheduled review, often within 90 days
A clear point of contact for questions
Review your plan at least once a year, and after any major life event: a sale, a death, a health change, or a market shift. The FINRA investor resources on managing your financial professional offers tools for monitoring your accounts and your advisor relationship.
If you’re within ten years of retirement or planning a business exit, schedule a consultation and walk in with a plan.
The decade before retirement is unforgiving. A market drop or a tax mistake can undo years of saving, and there’s no paycheck left to patch the hole.
Frequently Asked Questions
What should I bring to a retirement planning strategy session?
Bring recent statements for every account: 401(k)s, IRAs, taxable brokerage accounts, bank accounts, and any pensions. Include your most recent tax return, an estimate of monthly expenses, your Social Security statement, and insurance policies. If you own a business, add profit-and-loss statements, a current valuation estimate, and any buy-sell agreements. A completed retirement planning checklist keeps the meeting focused so your advisor spends time on strategy rather than gathering basics.
How do I know if I am ready for a retirement strategy session?
You are ready when you can describe your desired retirement lifestyle and have a rough idea of your current savings across all accounts. There is no minimum asset level required for a first conversation. If you are within ten years of your target retirement date, or you own a business you plan to sell, scheduling a session now gives you more time to adjust savings contributions, investment risk, and tax strategy before those decisions become urgent.
What is the difference between a financial advisor and a retirement strategist?
A financial advisor may focus primarily on managing investments. A retirement strategist coordinates investments, tax planning, insurance, and income withdrawal into one plan. The distinction matters most in the decade before retirement, when a market drop or tax mistake can affect how long your savings last. Ask any advisor how they integrate these areas and whether they act as a fiduciary, meaning they are required to put your interests first.
What tax implications should be discussed in a retirement planning session?
Discuss the order in which you will withdraw from taxable, tax-deferred, and tax-free accounts, since sequencing affects your tax bill each year. Ask about Roth conversion opportunities in lower-income years before required distributions begin. If you own a business, cover how the sale proceeds will be taxed and whether an installment sale or other structure fits your timeline. Tax rules change, so confirm current thresholds with your advisor or a tax professional rather than relying on outdated figures.
 By ira
October 11, 2026